Free zones at a crossroads: Why Nigeria must not tax away its industrial ambition

Nigeria’s ambition to build a $1 trillion economy will ultimately be tested not by the elegance of its policies but by the number of factories it attracts, the volume of goods it produces, the exports it generates and the billions of dollars in capital it can persuade investors to commit for the long term.
That is why the unfolding debate over Nigeria’s free-zone regime deserves greater attention. At stake is not merely a disagreement over tax administration but the future of a policy framework designed to attract investment, promote industrialisation and strengthen the country’s export capacity.
The central question is whether Nigeria’s free zones will remain internationally competitive investment destinations or gradually become conventional business locations stripped of the fiscal and regulatory advantages that initially attracted investors.
The draft Nigeria Export Processing Zones (Domestic Sales, Fiscal Alignment and Customs Treatment) Regulations, 2026, obtained for this report, provides a revealing insight into the proposed changes. Issued under the Nigeria Export Processing Zones Act and the Nigeria Tax Act 2025, the draft seeks to improve investor confidence, protect government revenue and enhance the global competitiveness of the zones.
Under the existing framework, approved enterprises enjoy exemptions from various taxes, levies and duties, alongside other incentives designed to attract investment. The draft regulations retain some of these exemptions but introduce significant conditions relating to domestic sales.
Under the proposal, an enterprise would qualify for tax exemption on profits only if at least 75 per cent of its annual turnover comes from exports and no more than 25 per cent from sales into Nigeria’s customs territory.
More significantly, from January 1, 2028, profits arising from domestic sales would be fully taxable, irrespective of the proportion of domestic sales to total turnover.
This represents a substantial shift in the fiscal treatment of free-zone enterprises and raises questions about the predictability of Nigeria’s investment policies.
Major policy changes of this nature require extensive consultation, particularly where investors have committed substantial capital under an established incentive regime. Abrupt changes to the rules risk undermining investor confidence and reinforcing concerns about policy inconsistency, which can discourage long-term investment.
However, nobody seriously committed to industrial development should defend the abuse of tax incentives. Companies that illegally divert duty-free goods into the domestic market should face appropriate sanctions.
The draft itself provides for customs duties, import VAT and other applicable charges on unauthorised movements of goods, alongside administrative penalties, seizure and possible prosecution for relevant offences.
The real policy challenge, therefore, is how to strengthen enforcement against abuse without eroding the incentives that distinguish free zones from conventional business locations.
Nigeria can achieve both objectives by retaining incentives, making them conditional on measurable economic performance, enforcing compliance rigorously and withdrawing benefits from enterprises that fail to meet their obligations. At the same time, investors who have complied with the law and committed long-term capital under existing approvals should receive appropriate protection.
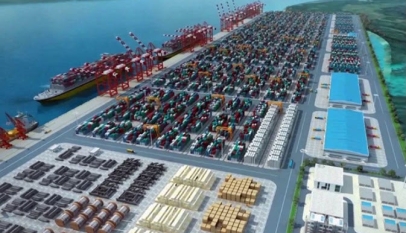
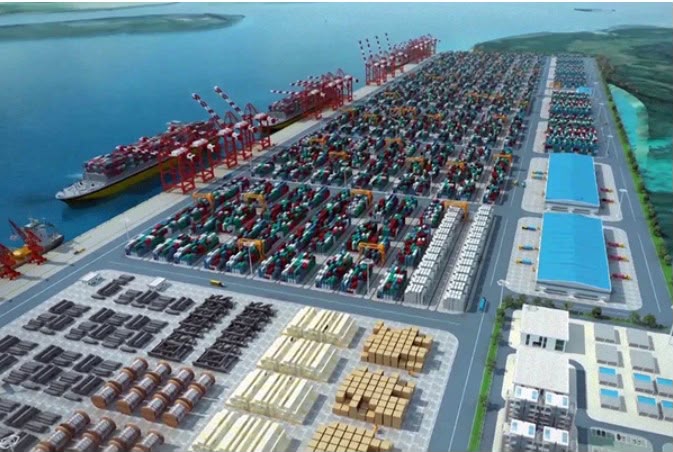
The Dangote lesson: Nigeria’s own industrial experience demonstrates the potential of free zones to attract large-scale investment. The Dangote Refinery and Petrochemical complex, located within the Dangote Industries Free Zone in Lekki, Lagos, illustrates how a free-zone ecosystem can support an industrial project of considerable scale. The project was initially facilitated by the Nigeria Export Processing Zones Authority (NEPZA) before its regulatory oversight was transferred to the Oil and Gas Free Zones Authority (OGFZA), a development that still warrants greater public explanation.
The broader economic lesson is that Nigeria’s free-zone framework can help attract and anchor investments that might otherwise be difficult to establish under the conventional domestic regulatory and fiscal environment.
Removing the economic advantages of the model raises an important question: what would persuade the next investor considering a refinery, petrochemical complex or other billion-dollar industrial project to choose a Nigerian free zone?
That question is particularly relevant as Nigeria competes with jurisdictions offering specialised regulatory frameworks, tax incentives, customs advantages and integrated infrastructure.
Investment decisions are also made over considerably longer periods than political cycles. A refinery, automobile factory, pharmaceutical plant or export-processing facility may require 10 to 25 years to recover its capital and generate expected returns. While governments can change tax policies relatively quickly, investors cannot relocate billion-dollar facilities overnight.
Policy consistency is therefore fundamental to Nigeria’s ability to attract and retain long-term industrial investment.
NEPZA’s regulatory role must remain clear: One of the most significant provisions in the draft regulations is its recognition of NEPZA’s continuing regulatory jurisdiction. Regulation 29 provides that NEPZA shall remain the exclusive regulator responsible for licensing, operational oversight, supervision and non-tax administration within the zones. The draft assigns tax administration to the Nigeria Revenue Service (NRS) and customs control and enforcement to the Nigeria Customs Service.
This division of responsibilities is logical. NEPZA should regulate the zones, the NRS should administer taxes, and Customs should oversee customs procedures and enforcement. However, the separation of these functions must not result in fragmented authority or conflicting regulatory directives.
The draft also provides for NEPZA, Customs and the NRS to jointly issue implementation guidelines covering domestic-sales thresholds, customs clearance, tax filing, audits, record-keeping, inspections and digital systems. While inter-agency collaboration is necessary, NEPZA must remain the institutional centre of operational regulation. Rather than diminish its authority, the government should strengthen its capacity to coordinate activities within the zones and ensure that its statutory responsibilities remain unambiguous.
The concerns raised by NEPZA workers over the proposed reforms also deserve serious consideration. Their opposition reflects concerns about the potential implications of the changes for foreign direct investment, employment and the Authority’s capacity to fulfil its mandate.
The government should therefore clarify the extent of NEPZA’s participation in developing the proposed regulations, identify the recommendations it submitted and explain which were accepted or rejected. Transparency in the policy process would help address concerns about inadequate consultation and strengthen confidence in the reforms.
Protect existing investment commitments: The draft regulations acknowledge that enterprises enjoying incentives validly granted before the commencement of the relevant legislation may continue to benefit from them for the unexpired portion of their statutory approval periods, subject to the applicable laws and original approvals.
They also provide that incentives cannot be extended beyond their statutory sunset periods except through legally authorised processes. However, the government must carefully distinguish between new incentives, existing approvals and incentives already incorporated into legally established investment commitments.
An investor who has already committed substantial capital under an existing government-approved framework is in a different position from one considering a new investment. Policy reforms should recognise this distinction to protect legitimate expectations without compromising the government’s revenue interests.
Nigeria must also establish whether the proposed changes will generate greater economic value through additional tax revenue or whether they could discourage investment, reduce industrial output and constrain future revenue growth.
The government should publish a comprehensive cost-benefit assessment of the free-zone incentive regime, examining its contributions to investment, employment, exports, industrial production and public revenue. Such an assessment would provide an evidence-based foundation for determining which incentives should be retained, modified or withdrawn.
Why NEPZA needs stronger presidential coordination: The free-zone programme cuts across taxation, customs, ports, immigration, infrastructure, trade, investment promotion, manufacturing and foreign exchange. Its success therefore requires coordination beyond the conventional boundaries of a single ministry.
Keeping NEPZA under a single ministry can expose a long-term national economic programme to changing policy priorities. A stronger presidential coordination mechanism could provide greater institutional stability without necessarily abolishing ministerial oversight.
The Federal Government could consider establishing a Presidential Special Economic Zones Council comprising NEPZA, OGFZA, the Ministries of Finance and Industry, Trade and Investment, the NRS, Customs, the Central Bank of Nigeria, port authorities, infrastructure agencies and private-sector representatives.
Such a council could develop a coherent national strategy for special economic zones, reconcile competing institutional priorities and ensure that revenue objectives do not undermine investment promotion.
The Ministry of Industry, Trade and Investment has maintained that the proposed reforms are intended to improve fiscal accountability while preserving the competitiveness of free zones.
The Minister, Dr Jumoke Oduwole, has also stated that NEPZA and OGFZA were involved in the reform process and would retain their licensing and operational responsibilities.
Nevertheless, the concerns surrounding the reforms must be examined against the historical relationship between the ministry and NEPZA.
The Authority’s union previously challenged actions taken during the tenure of former Minister of Industry, Trade and Investment, Dr Okechukwu Enelamah, over a proposed arrangement involving the transfer of public funds to a private entity.
The union raised concerns over the withdrawal of ₦14.38 billion from NEPZA’s capital project budget account and its transfer to the Nigerian Special Economic Zones Company, which it alleged was registered as Nigeria Sez Investment Company Limited.
The matter attracted the attention of the National Assembly, with the Senate and the House of Representatives Committee on Commerce questioning the arrangement. The Senate subsequently directed that the funds be returned to the national treasury.
This history provides important context for understanding the union’s scepticism towards proposals that it believes could weaken NEPZA’s institutional authority. However, the current reforms should be assessed on their merits, with particular attention to their likely effects on investment and the Authority’s statutory responsibilities.
If evidence establishes that the proposed regulations could undermine investment, weaken investor confidence or make Nigeria less competitive than rival free-zone jurisdictions, the President should intervene to ensure that the framework is reviewed.
Modernise the NEPZA Act to attract investment: Beyond the immediate debate over taxation, the more fundamental challenge is the age and limitations of the NEPZA Act of 1992.
Much of the legislation was designed for an earlier phase of Nigeria’s industrial development. The free-zone industry has since evolved, with modern investment increasingly dependent on complex financing arrangements, technology partnerships, digital trade, infrastructure development and sophisticated international commercial relationships.
The existing legal framework needs to accommodate these developments. Its limitations risk creating regulatory uncertainty for foreign investors who require clear rules on governance, ownership, financing, dispute resolution, investor protection and commercial operations.
Outdated provisions may also constrain corporate flexibility, infrastructure financing, public-private partnerships, concessions and the development of modern industrial parks.
These limitations could undermine the Authority’s ability to attract the scale of investment required to expand Nigeria’s manufacturing and export capacity.
Consequently, Oduwole should take the initiative to promote an Executive Bill through the Federal Executive Council to replace the existing NEPZA Act with a modern Special Economic Zones framework.
The proposed legislation should provide a more flexible and internationally competitive model, with clear provisions for investment incentives, regulatory coordination, governance, financing, investor protection and operational oversight.
Such a reform would allow Nigeria to move beyond a framework primarily designed around export processing and develop a broader special economic zones system capable of accommodating the changing needs of global investors.
Importantly, modernising the Act would also provide an opportunity to clarify the respective responsibilities of NEPZA, OGFZA, the NRS and Customs, reducing the risk of regulatory overlap and institutional conflict.
The Presidency must look beyond the tax ledger: President Bola Ahmed Tinubu’s $1 trillion economic ambition requires a stronger emphasis on productive capacity. Factories, exports, petrochemicals, industrial parks and special economic zones should form a central part of the strategy to expand Nigeria’s economy.
Investors are more likely to make long-term commitments when the regulatory and fiscal conditions under which they enter the market are sufficiently predictable.
The Dangote experience illustrates the potential contribution of free zones to large-scale industrial development. However, replicating such investments requires more than offering incentives. It also requires reliable infrastructure, efficient customs administration, regulatory clarity and confidence that government policies will remain consistent.
Investment incentives should therefore be treated as instruments for attracting productive capital, rather than ends in themselves.
In this regard, the existing presidential authorisation permitting free-zone operators to sell 100 per cent of their products into the Nigerian customs territory should be maintained pending a comprehensive amendment of the NEPZA Act. Any subsequent changes should follow transparent consultations and a clear assessment of their economic implications.
The government has every right to demand accountability from free-zone operators, prevent the diversion of duty-free goods and ensure that enterprises benefiting from incentives deliver measurable investment, employment and export gains. It also has a legitimate responsibility to collect taxes and duties lawfully due on domestic transactions.
These objectives are not mutually exclusive. They can coexist with investment incentives, rigorous audits, effective customs enforcement, modern tax administration and a strong NEPZA.
The final test
Before implementing fundamental changes to the free-zone regime, the Federal Government should consider whether the proposed framework will make Nigeria more attractive to investors contemplating projects worth $500 million, $1 billion or $5 billion.
If the reforms can achieve greater fiscal accountability while preserving investment competitiveness, they would serve both revenue and industrial development objectives. Where their implications remain uncertain, wider consultations and further assessments are necessary. Where evidence points to a decline in competitiveness, the reforms should be reconsidered.
Ultimately, Nigeria needs a free-zone system that is firm against abuse but supportive of productive investment, rigorous in enforcing compliance but predictable in granting incentives, and coordinated across government without compromising the statutory authority of its regulator.
NEPZA should not be weakened because the free-zone regime requires reform. Rather, its regulatory capacity should be strengthened to support the reforms and safeguard the integrity of the system.
The government must recognise that the existing legislation itself requires urgent modernisation. Replacing the 1992 Act with a comprehensive and globally competitive Special Economic Zones law would address many of the structural limitations confronting the Authority and provide a more sustainable foundation for investment.
Nigeria’s ambition to become a $1 trillion economy will require more than policy declarations and additional tax revenue. It will depend on factories, industrial infrastructure, jobs, exports and investors willing to commit substantial capital over decades.
The challenge for the Federal Government is to reform the free-zone regime without undermining the very investment proposition it was established to protect.